Technip and KPSP sign service agreement for Kazakhstan oilfield Offshore Technology
The post Technip and KPSP sign service agreement for Kazakhstan oilfield – Offshore Technology first appeared on The Russian World.
 The World Web Times - worldwebtimes.com
The post Technip and KPSP sign service agreement for Kazakhstan oilfield – Offshore Technology first appeared on The Russian World.
Strong wind pushed the larger of two wildfires into the mountain village of Ruidoso, forcing residents to flee immediately with little notice. Weather patterns are expected to shift by Wednesday morning with moisture from a tropical wave in the Gulf of Mexico, said Joshua Schroeder of the National Weather Service in Albuquerque.
“Today was really our last dry day,” he said late Tuesday. “Rains will then peak into Thursday and diminish by the weekend.”
On the downside, he said, some shifts in wind were possible later Wednesday, and rain could lead to flash flooding in newly burned areas.
Ruidoso and much of the Southwest has been exceedingly dry and hot this spring. Those conditions, along with strong wind, whipped flames out of control Monday and Tuesday, rapidly advancing the South Fork Fire into the village. Along with homes and businesses, a regional medical center and the Ruidoso Downs horse track were evacuated.
Gov. Michelle Lujan Grisham’s office confirmed one fatality as a result of the fire but said it had no further details.
More than 500 structures have been destroyed or damaged, but it’s unclear how many were homes. A flyover to provide more accurate mapping and a better assessment of damage was planned overnight Tuesday, Lujan Grisham said.
Ardis Holder left Ruidoso with her two young daughters, her gas tank nearly on empty and praying that they’d make it out safe. She was sure the house she rented in the village she grew up in is gone, based on the maps she’s seen so far.
“We were already seeing where all the fire hit, it’s everywhere,” she said late Tuesday from a shelter in nearby Roswell. “If there’s something standing, that’s awesome. But, if not, we were prepared for the worst.”
Lujan Grisham declared a county-wide state of emergency that extended to the neighboring Mescalero Apache Reservation where both fires started and deployed National Guard troops. The declaration unlocks additional funding and resources to manage the crisis.
Nationwide, wildfires have scorched more than 3,280 square miles (8,495 square kilometers) this year — a figure higher than the 10-year averages, according to the National Interagency Fire Center. About 20 wildfires currently burning are considered large and uncontained, including blazes in California and Washington state.
Lujan Grisham said the two southern New Mexico wildfires together have consumed more than 31 square miles (80 square kilometers). The exact causes of the blazes hasn’t been determined, but the Southwest Coordination Center listed them as human-caused.
“We are deploying every available resource to control these fires.” she said.
While many older residents call Ruidoso home year-round, the population of around 7,000 people expands to about 25,000 during the warmer months, when New Mexicans and Texans from hotter climates seek the cool of the leafy aspen trees, hiking trails and a chance to go fishing.
Nestled within the Lincoln National Forest, Ruidoso boasts nearby amenities including a casino, golf course and ski resort operated by the Mescalero Apache Tribe. Horse races at the Ruidoso Downs also draw crowds as home to one of the sport’s richest quarter-horse competitions.
Ruidoso residents fled Monday through traffic-clogged downtown streets some described as apocalyptic, with smoke darkening the evening sky, embers raining down and 100-foot (30-meter) flames in the distance climbing over a ridgeline.
The evacuation order came so quickly that she Christy Hood and her husband Richard only had time to grab their two children and two dogs. Heavy traffic on the way out turned what should have been a 15-minute drive into a harrowing two-hour ordeal.
“As we were leaving, there were flames in front of me and to the side of me,” said Hood, a real estate agent in Ruidoso. “And all the animals were just running — charging — trying to get out.”
On social media posts, Ruidoso officials didn’t mince words: “GO NOW: Do not attempt to gather belongings or protect your home. Evacuate immediately.”
As Jacquie and Ernie Escajeda left church Monday in Ruidoso, they saw smoke rise above a mountain behind their house.
They kept a close eye on their cellphones and turned on the radio for updates. There was no “get ready,” nor “get set” — it was just “go,” Ernie Escajeda said. They grabbed legal documents and other belongings and left.
On Tuesday, the couple got a call from friends who are on vacation in Utah but have a home in Ruidoso that they’ve been told was destroyed, Jacquie Escajeda said.
“They lost their home,” she said. “There’s only one home standing in their whole little division that they live in, so there are a lot of structures lost. We have no idea if we’re going to have a home to go to.”
Public Service Company of New Mexico shut off power to part of the village due to the fire.
Lujan Grisham said cellphone service had been affected in some communities near the fire, and mobile cell towers were being set up to restore communications.
Amid highway closures, many evacuees had little choice but to flee eastward and to the city of Roswell, 75 miles (121 kilometers) away, where hotels and shelters quickly filled. A rural gas station along the evacuation route was overrun with people and cars.
Brittany Chang/Business Insider
Silversea is one of the highest-end cruise lines on the market. So, as you can imagine, its new ship’s most expensive suites are luxurious.
Like, really luxurious. And really expensive.
Silversea’s new Silver Ray departed on its maiden voyage in mid-June. As is expected of Royal Caribbean Group’s ritziest brand, the cruise line’s 12th ship is outfitted with 364 of some of the most sumptuous suites at sea, the smallest of which already have a balcony, marble bathroom, and on-demand caviar.
Brittany Chang/Business Insider
Well, after seeing Silver Ray’s most glamorous 1,324-square-foot Otium Suites, you could find yourself scoffing at its other accommodations.
Its balcony alone is larger than the ship’s smallest suites. And its cost is more than three times that of the cheapest option.
Brittany Chang/Business Insider
It’s a steep price compared to the itinerary’s least expensive $4,850 per person suite (there’s an even cheaper category, but it’s sold out for the sailing).
Brittany Chang/Business Insider
Upon entering, you’re immediately greeted with the library and dining room — spaces you’d be hard-pressed to find in a typical cruise cabin.
Forgot a book? The reading nook is perfectly stocked for travelers interested in learning about bicycle brand Brompton (“The Brompton” by Will Butler-Adams and Dan Davies) and British microchip maker Arm (“The Everything Blueprint: The Microchip Design that Changed the World” by James Ashton).
Or, grab one of the neatly packaged games, such as tic-tac-toe and dominoes.
Brittany Chang/Business Insider
If you enjoy playing with a side of snacks, the fresh fruit bowl might do. Otherwise, you could call your butler for complimentary caviar or foie gras.
If it looks like a long game, brewing one of the bar’s espresso pods or teas might be a good idea. Or, help yourself to some liquor, stocked according to the guests’ preferences.
Brittany Chang/Business Insider
The couch can convert into a bed to sleep an additional guest. There’s certainly ample room for three travelers, after all.
Take note of the chessboard and fresh-cut flowers, small touches that are, again, uncommon in the average suite.
Brittany Chang/Business Insider
It’s also where you’ll find the vanity, walk-in closet, and sizable bathroom — decorated with marble, of course.
Brittany Chang/Business Insider
To out-luxe these cheaper accommodations, the Otium Suite comes with both a shower and a bathtub.
No need to worry about full privacy. The toilet is behind another closed door.
Brittany Chang/Business Insider
There’s no need to hit the pool deck when your 431-square-foot balcony has a private hot tub, lounge chairs, and an outdoor dining table.
To compare, Silver Ray’s smallest suites come with a 53-square-foot balcony. Size does matter, after all.
Brittany Chang/Business Insider
Hey, at least the cost includes a $399 spa treatment per person, too. Maybe a luxurious massage would help melt away the stress of the payment.
The offers and details on this page may have updated or changed since the time of publication. See our article on Business Insider for current information.
Affiliate links for the products on this page are from partners that compensate us and terms apply to offers listed (see our advertiser disclosure with our list of partners for more details). However, our opinions are our own. See how we rate banking products to write unbiased product reviews.
Banks are fighting for customer dollars right now, and people with cash to spare are well-positioned to benefit from a high rate environment. With rates rapidly changing, how can you feel confident that you’re getting the best savings account or best CD?
We monitor rates from banks and credit unions daily to help you feel confident before you open a new account. Experts don’t expect CD rates to go up in 2024, so now could be a great time to lock in a rate if you’re ready. Here are the top rates for popular savings accounts and CDs on Wednesday, June 19.
| Account Name | APY (Annual Percentage Yield) Accurate as of 6/17/2024 | Minimum Account Opening Balance |
| Western Alliance Bank High-Yield Savings Premier | 5.36% | $500 |
| BrioDirect High-Yield Savings Account | 5.30% | $5,000 |
| Forbright Growth Savings | 5.30% | $0 |
| CIT Bank Platinum Savings | 5.00% (with $5,000 minimum balance) | $100 |
| Capital One 360 Performance Savings | 4.25% | $0 |
| Account Name | APY (Annual Percentage Yield) Accurate as of 6/17/2024 | Minimum Account Opening Balance |
| Barclays 1 Year Online CD | 5.00% | $0 |
| Banc of California 3 Month CD, powered by Raisin | 5.34% | $1 |
| Barclays 6 Month Online CD | 4.85% | $0 |
| SkyOne Federal Credit Union 1 Year No Penalty CD | 4.75% | $1 |
| Discover 18 Month CD | 4.40% | $2,500 |
| Bread Savings 2 Year High-Yield CD | 4.65% | $1,500 |
| Quontic 5 Year CD | 4.30% | $500 |
Alliant High-Rate Savings Account
Earn a $100 bonus when you deposit at least $100 a month for 12 consecutive months and have a balance of $1,200 or more at the end of the 12-calendar-month period (offer expires December 31, 2024).
See more savings account bonuses »
Earn up to $300 with qualifying direct deposit for eligible customers (offer expires 12/31/24). Earn up to 4.60% APY on savings balances (including Vaults) with direct deposit.
See more bank account bonuses »
High-yield savings accounts aren’t the only accounts paying favorable rates right now. You’ll typically see the highest rates at online or lower-profile institutions rather than national brands with a significant brick-and-mortar presence. This is normal; online banks have lower overhead costs and are willing to pay high rates to attract new customers.
The best high-yield savings accounts provide the security of a savings account with the added bonus of a high APY. Savings accounts are held at a bank or credit union — not invested through a brokerage account — and are best for saving cash in pursuit of shorter-term goals, like a vacation or big purchase.
The best high-yield checking accounts tend to pay slightly lower rates than high-yield savings, but even they are strong in today’s rate environment. A checking account is like a hub for your money: If your paycheck is direct deposited, it’s typically to a checking account. If you transfer money to pay a bill, you typically do it from a checking account. Checking accounts are used for everyday spending and usually come with checks and/or debit cards to make that easy.
The best money market accounts could be considered a middle ground between checking and savings: They are used for saving money but typically provide easy access to your account through checks or a debit card. They usually offer a tiered interest rate depending on your balance.
A cash management account is also like a savings/checking hybrid. You’ll generally see them offered by online banks, and, unlike a checking account, they usually offer unlimited transfers. A savings account often limits the number of monthly transfers, while a checking account doesn’t. Cash management accounts typically come with a debit card for easy access, but you may have to pay a fee if you want to deposit cash.
The best CD rates may outpace any of the other accounts we’ve described above. That’s because a certificate of deposit requires you to “lock in” your money for a predetermined amount of time ranging from three months to five years. To retrieve it before then, you’ll pay a penalty (unless you opt for one of the best no-penalty CDs). The longer you’ll let the bank hold your money, the higher rate you’ll get. CD rates aren’t variable; the rate you get upon depositing your money is the rate you’ll get for the length of your term.
Locking your money into an account in exchange for a higher interest rate can be a big decision. Here’s what you need to know about common CD terms.
Most CDs charge you a fee if you need to withdraw money from your account before the term ends. But with a no-penalty CD, you won’t have to pay an early withdrawal penalty. The best no-penalty CDs will offer rates slightly higher than the best high-yield savings accounts, and can offer a substantially improved interest rate over traditional brick-and-mortar savings accounts.
The best 6-month CDs are offering interest rates in the mid-5% range. Six-month CDs are best for those who are looking for elevated rates on their savings for short-term gains, but are uncomfortable having limited access to their cash in the long term. These can be a good option for those who may just be getting started with saving, or who don’t have a large emergency fund for unexpected expenses.
The best 1-year CDs tend to offer some of the top CD rates, and are a popular option for many investors. A 1-year term can be an attractive option for someone building a CD ladder, or for someone who has a reasonable cash safety net but is still concerned about long-term expenses.
The best 2-year CD rates will be slightly lower than 1-year and no-penalty CD rates. In exchange for a longer lock-in period, investors receive a long-term commitment for a specific rate. These are best used as part of a CD ladder strategy, or for those worried about a declining rate market in the foreseeable future.
The best 3-year CDs tend to have rates that are comparable to 2-year CDs. These are usually less popular for your average investor, but can be an important lever when diversifying investments and hedging against the risk of unfavorable rate markets in the long term.
The best 5-year CDs will offer lower rates than the other terms on our list, but are still popular options for investors. These CDs are best for those looking to lock in high rates for the long term. CDs are generally viewed as safe investment vehicles, and securing a favorable rate can yield considerable earnings in year three and beyond — even if rates fall elsewhere.
The offers and details on this page may have updated or changed since the time of publication. See our article on Business Insider for current information.
Affiliate links for the products on this page are from partners that compensate us (see our advertiser disclosure with our list of partners for more details). However, our opinions are our own. See how we rate mortgages to write unbiased product reviews.
According to data from Zillow, 30-year mortgage rates are currently hovering at 6.62%. This is down from early May, when rates hit 7.11%.
Rates could continue to decrease if inflation cools, but don’t expect a huge drop this year. According to the Mortgage Bankers Association’s latest forecast, mortgage rates may fall to 6.5% by the end of 2024.
Waiting until 2025 could be your best bet if you want to snag even lower rates. If you’re looking to buy a home sooner than later, make sure you shop around and compare rates with multiple mortgage lenders to get the best deal.
Use our free mortgage calculator to see how today’s mortgage rates would impact your monthly payments. By plugging in different rates and term lengths, you’ll also understand how much you’ll pay over the entire length of your mortgage.
Click “More details” for tips on how to save money on your mortgage in the long run.
The average 30-year fixed mortgage rate was 6.95% last week, according to Freddie Mac. This is a four-basis-point decrease from the previous week.
The 30-year fixed-rate mortgage is the most common type of home loan. With this type of mortgage, you’ll pay back what you borrowed over 30 years, and your interest rate won’t change for the life of the loan.
The lengthy 30-year term allows you to spread out your payments over a long period of time, meaning you can keep your monthly payments lower and more manageable. The trade-off is that you’ll have a higher rate than you would with shorter terms or adjustable rates.
Last week, average 15-year mortgage rates were 6.17%, a 12-basis-point decrease from the previous week, according to Freddie Mac data.
If you want the predictability that comes with a fixed rate but are looking to spend less on interest over the life of your loan, a 15-year fixed-rate mortgage might be a good fit for you. Because these terms are shorter and have lower rates than 30-year fixed-rate mortgages, you could potentially save tens of thousands of dollars in interest. However, you’ll have a higher monthly payment than you would with a longer term.
Mortgage rates started ticking up from historic lows in the second half of 2021 and increased over three percentage points in 2022. Rates also increased dramatically last year, though they trended back down toward the end of 2023.
As inflation comes down, mortgage rates will recede as well. Most major forecasts expect rates to go down later in 2024.
For homeowners looking to leverage their home’s value to cover a big purchase — such as a home renovation — a home equity line of credit (HELOC) may be a good option while we wait for mortgage rates to ease. Check out some of our best HELOC lenders to start your search for the right loan for you.
A HELOC is a line of credit that lets you borrow against the equity in your home. It works similarly to a credit card in that you borrow what you need rather than getting the full amount you’re borrowing in a lump sum. It also lets you tap into the money you have in your home without replacing your entire mortgage, like you’d do with a cash-out refinance.
Current HELOC rates are relatively low compared to other loan options, including credit cards and personal loans.
The Federal Reserve increased the federal funds rate a lot last year to try to slow economic growth and get inflation under control. Inflation has come down a lot in response to this, though it’s still a little bit above the Fed’s target rate of 2%.
Mortgage rates aren’t directly impacted by changes to the federal funds rate, but they often trend up or down ahead of Fed policy moves. This is because mortgage rates change based on investor demand for mortgage-backed securities, and this demand is often impacted by how investors expect Fed hikes to affect the broader economy.
Fed hikes have pushed mortgage rates up over the last two years. But the Fed has indicated that it’s likely done hiking rates and could start cutting in 2024. Once the Fed cuts rates, mortgage rates should fall even further.
Imagine living 10 minutes away from your favorite golf course. Not only could you sleep in a little bit later if you have an early tee time, but you could probably play multiple rounds in a single day. Plus, there won’t be any debate about who will be hosting weekend get-togethers. Your friends will happily make their way over to your place.
Download our free golf cart policy template
Some homeowners are lucky enough to live in a community with a golf course. But this setup isn’t always as beneficial as it may seem.
Golf homes are popular in warm states like Florida, Texas, and Arizona, since it is possible to play a round all year long. However, golf courses have struggled financially for several years (though there has been a recent reversal in this trend) thus diminishing the appeal of these communities. That’s because the success of the course has a direct impact on the HOA.
Table of contents
Membership is as unique as the course. Some clubs require homeowners to pay for a membership, while others make it optional.
It can be very expensive to live in a golf community, but homes in these areas may sell for 20% to 50% more than similar homes not located near a golf course.
While this article won’t cover everything there is to know about HOAs and golf clubs, it will touch on the most important points.
There are multiple options when it comes to buying a home on or next to a golf course.
Location
or
Ownership
but
Membership
but
Equity membership
Non-equity membership
Accessibility
or
Additional considerations
Fees for club membership may be included with association dues, or owners may be expected to pay separately for a membership. Homeowners may also be offered some sort of discount, but there is no such thing as free golf.
Prospective buyers should consider hiring a real estate agent who specializes in golf communities to help them make sense of all of the intricacies that accompany golf communities.
A POA, or a property owners association, is a term used to describe an organization that manages and governs a community or residential area. A POA may encompass multiple HOAs.
The primary goal of a POA is to ensure the overall well-being of the community and to maintain common areas, shared amenities, and common property.
Like HOAs, POAs charge property owners regular fees to cover the costs of maintaining shared spaces, or in this case, the golf course and related amenities. However, POAs do not govern individual lots and homes the way HOAs do.
So, a golf community may be a part of an HOA and a POA at the same time.
Every golf course is unique, as are each club’s price structures and fees. Fortunately, many golf courses have their prices listed on their websites.
The amount you pay could range anywhere from $100 for a day, to $100,000 for an equity membership. That is usually in addition to regular HOA dues.
Equity membership
Depending on the number of members and exclusivity of the club, the initial membership fee or deposit can range from $5,000 to more than $250,000. However, much or all of this fee is refundable upon resignation from the club. If the membership fee has appreciated in value, the member benefits from that appreciation.
There is also an annual fee (dues), a trail fee or cart rental fee, and taxes.
Most equity arrangements require members to spend a minimum amount each year on food, drinks, and other clubhouse amenities. If the minimum is not reached, the member is charged for the difference.
Non-equity membership
Non-equity members pay fees, but aren’t making the investment that equity members make. Instead, they are free to show up and play a round while enjoying the clubhouse lifestyle without having to take on any ownership responsibilities.
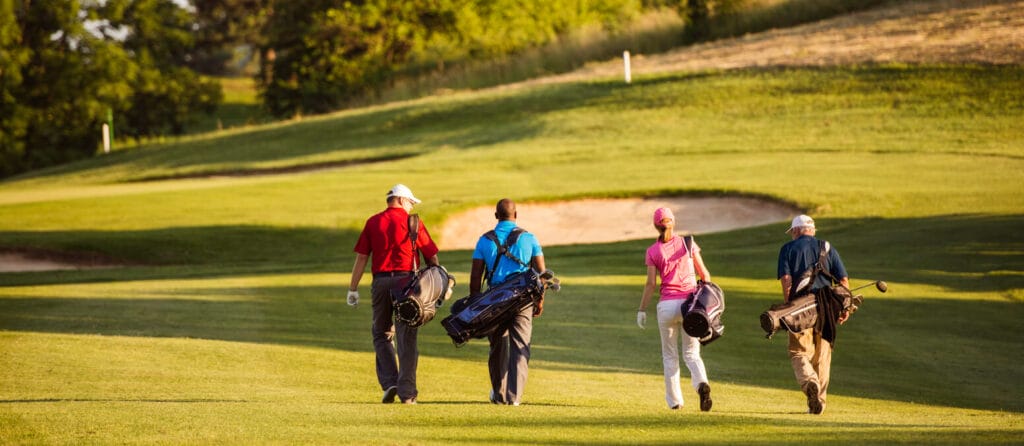
Non-equity initiation fees are roughly just over half the cost of an equity membership fee, so if equity members paid a one-time fee of $50,000, a non-equity member might be required to pay $35,000.
Speaking of fees, non-equity membership was traditionally a non-refundable program, however, many clubs have changed the old model. Now, non-equity members may receive a percentage of the initial deposit after they leave the club, but they won’t benefit from any value appreciation.
Annual membership
Annual memberships for people belonging to HOAs cost, on average, $5,000 to $8,000 depending on the amenities, package deals, and the exclusivity of the club. Guests may pay $7,000 to $10,000 for the same annual membership.
Initiation fees are generally a few thousand dollars. Golfers may be given the option to pay a higher, refundable initiation fee, or lower, non-refundable initiation fee.
Day pass
Day passes may not be available, but if they are, they can range from less than $100 to about $300.
Trail fees
We only mentioned trail fees under the equity membership section, but theoretically, they can apply to all types of memberships. Trail fees cover the use of golf carts on the course. The money is used to cover the cost of maintaining the course.
Trail fees can cost as little as $5 per person, per use, and annual fee options may be available. This fee may apply to private carts only, or both club-owned and private carts.
If a golfer walked to every hole, they would cover at least 4 miles, but many courses would require you to walk even more. That’s why golfers opt to use a golf cart instead.
Golf clubs generally have carts available for rent, but avid golfers prefer their own carts.
While they are convenient (and fun to operate) golf carts must adhere to strict rules in order to keep people and property safe. Furthermore, cart owners must have insurance to cover accidents. Carts are also required to undergo a safety inspection to ensure they are course-compliant.
HOAs centered around golf courses almost always have a golf cart policy or agreement for owners to follow/sign.
The policy or agreement will outline penalties for breaking golf cart rules. Usually, the penalties are monetary fines ranging from $50 to $500.
Living next to a golf course is a dream for some. Here are a few reasons why HOA golf communities are the perfect place to call home:
There are several good reasons to live in a golf course community, but there are some significant cons that prospective buyers need to think about as well:
Golf communities create the perfect living environment for avid golfers. There are a lot of advantages to living in an HOA with a golf course, but it’s critical that prospective buyers do their research before submitting a bid or signing a contract. Not all golf communities are created equally.
The HOA and the golf course must both be in a good financial position, and regular maintenance is non-negotiable. The demographics, membership structure and fees will also help determine whether the community is the right fit for you.
The post HOAs and golf courses appeared first on Condo Control.
The post HOAs and golf courses first appeared on The Condo Law.
World News – 2024 – Video Playlist | Video Playlists | Sites: | newsandtimes.org | links-newsandtimes.com | worldwebtimes.com | southcaucasusnews.com | russianworld.net | jossica.com | octobersurprise2016.org | bklyntimes.com | oceanavenuenews.com | fbireform.com | bloggersunite.net | octobersurprise-2024.org | Trump-News.org | Audio-Posts.com | Bklyn-NY.com | Posts Review – newsandtimes.org